Cracking the Gold Code: Price Drivers and Your Path to Ownership
Gold has long captured the attention of investors seeking to preserve wealth and diversify their portfolios. But with prices moving in response to changing market conditions, is gold still worth considering?
Gold’s investment appeal should be assessed against prevailing prices, interest rates and currency movements, alongside the possibility of further gains or corrections. While economic uncertainty can strengthen demand for gold, its price is influenced by multiple factors, and past performance does not guarantee future returns.
For investors, the key is to understand what drives gold prices, the risks involved and how gold might fit into a broader investment strategy.
Understanding the factors behind gold prices
Gold prices are shaped by a combination of monetary conditions, central-bank activity, inflation expectations, currency movements and investor sentiment. Here are three important factors to consider.
-
Central-bank accumulation
Central banks may hold gold as part of their official reserve assets to diversify their assets and reduce reliance on individual currencies. Their purchases can provide an important source of demand for the precious metal.
Central-bank reserve diversification can support gold demand, although purchases may fluctuate and can be outweighed by selling elsewhere in the market. While reserve diversification is an important market consideration, it does not guarantee that gold prices will continue to rise.
-
Interest rates and real yields
Gold does not generate interest or dividends, making its relative attractiveness sensitive to the returns available from other investments.
Gold remains sensitive to changes in interest-rate expectations. Lower real yields can support its appeal, while higher real yields can weigh on prices. Real yields measure investment yields after accounting for expected or realised inflation, depending on the measure used.
Rather than assuming that interest-rate cuts will automatically push gold higher, investors should monitor changes in real yields and monetary-policy expectations alongside other market developments. -
Inflation, the US dollar and currency movements
Gold is often viewed as a potential store of value during periods of inflation concerns or economic uncertainty. However, inflation alone does not ensure stronger gold prices.
Gold’s performance depends partly on the interaction between inflation, real yields and the US dollar. Inflation concerns may support demand, while higher real yields or a stronger dollar can offset that support.
For Malaysian investors with unhedged exposure, gold returns also depend on USD/MYR. Ringgit weakness can enhance MYR returns, while ringgit strength can reduce them. Currency movements can therefore amplify or offset changes in the US-dollar price of gold.
Ultimately, gold prices reflect both longer-term demand and short-term investment flows. Longer-term buying does not eliminate volatility or the risk of corrections.
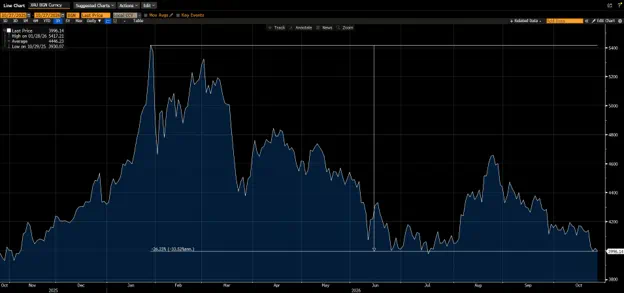 Source: Bloomberg 27 October 2026
Gold has corrected approximately 26% from its January 2026 peak. For investors considering gold as part of a diversified portfolio, the recent pullback may offer a more attractive entry point compared with earlier highs.
Gold: The missing piece in your investment puzzle?
Wondering whether you have missed the opportunity to invest in gold? Should you wait for prices to fall before buying?
There is no easy answer. Market timing is difficult, and waiting for a correction does not guarantee a better entry point. Equally, buying after a strong rally carries the risk that prices may subsequently decline.
A more useful question is: what role could gold play in your portfolio?
A broader base of demand
Central-bank purchases, investment demand and jewellery consumption can all influence the gold market. Investors can also access gold through exchange-traded funds (ETFs) and other investment products.
However, it would be premature to conclude that longer-term demand makes gold less speculative or less volatile than during previous rallies. Prices continue to respond to changes in investor positioning, interest-rate expectations and market sentiment.
Inflation and purchasing power
Gold is often considered during periods of inflation concerns because investors may seek assets that could help preserve purchasing power over time.
However, its effectiveness as an inflation hedge varies across market conditions and investment horizons. Higher real yields or a stronger US dollar may offset inflation-related support, and gold prices can fall even when inflation remains elevated.
Structural shifts and market uncertainty
Geopolitical developments, changes in central-bank reserve strategies and uncertainty surrounding the global economy can influence demand for gold.
These longer-term developments may support investment interest, but they should not be treated as a guarantee of continued price appreciation. Investors should consider both the underlying drivers and the possibility of short-term market corrections.
Rethinking gold’s role
Instead of asking, “Is it too late to buy gold?”, consider asking, “What role could gold play in diversifying my portfolio?”
Gold does not generate corporate earnings or pay dividends. Its investment performance depends largely on changes in its market price, which can be influenced by monetary conditions, demand and investor sentiment.
Gold can provide diversification because its performance does not always move in the same direction as equities and bonds. However, diversification benefits vary over time, and gold prices can decline alongside other investments. Price declines may also be prolonged.
For investors, the objective is not necessarily to maximise gold holdings or chase recent gains. It is to determine whether an allocation complements existing investments and supports their broader financial objectives.
The appropriate allocation will depend on individual circumstances, including risk tolerance, investment horizon, liquidity needs and overall portfolio composition. There is no single allocation that suits everyone.
Before you buy… read this
Gold can offer diversification benefits, but investors should weigh its potential advantages against several risks.
- Higher real yields: A stronger-than-expected economic outlook or changing monetary-policy expectations may push real yields higher, making interest-bearing investments relatively more attractive.
- A stronger US dollar: Dollar strength can weigh on US-dollar gold prices, although the relationship is not consistent in every market environment.
- Profit-taking and price corrections: Following substantial gains, investors may sell gold to realise profits. Corrections can be sharp, and prices may take time to recover.
- Currency fluctuations: For Malaysian investors with unhedged exposure, movements in USD/MYR can increase or reduce returns in ringgit terms.
- Changing diversification benefits: Gold may not move independently of equities and bonds in every market environment. Investors should be prepared for the possibility of simultaneous losses across different assets.
These considerations do not negate gold’s potential role in a portfolio. They reinforce the importance of viewing it as a measured allocation rather than an all-in bet.
How to own gold
Investing in gold is more convenient — and varied — than ever. Lining up outside the jeweller’s is now just one of many options, some only requiring a few clicks on an app.
-
Physical gold
Bars, coins, or jewellery appeal to traditionalists. They offer satisfaction but require secure storage and incur premiums. -
Exchange-traded funds (ETFs)
ETFs like the iShares Gold ETF (CH), held via the RHB Gold Fund, track spot prices closely and provide liquidity without the hassle of storage. -
Gold-linked funds
The RHB Gold Equity Fund provides exposure to global mining and metals companies, with potential gains and losses influenced by commodity prices and company-specific risks. -
Structured or dual-currency products
For investors seeking enhanced yield, Dual Currency Gold Investment (DCI Gold) links returns to gold and foreign-exchange movements, but is not principal-protected or PIDM-protected and is subject to suitability assessment. -
Paper gold
RHB allows paper gold/silver investment in a Multi Currency Account without physical storage, subject to prevailing transaction requirements, charges and terms, with these gold/silver investments.
For experienced investors, combining several of these can turn gold exposure into a multi-layered strategy that includes physical holdings for legacy, ETFs for liquidity, and structured notes for tactical plays. For newer investors, starting small through a regulated fund or digital-gold app can offer flexibility, although capital remains at risk. Your Relationship Manager will be able to help you establish an approach that works for your goals and risk appetite.
Purpose, not price
At its core, gold remains a paradox: it doesn’t yield interest, it doesn’t generate profits, yet it endures. Gold may help diversify a portfolio during uncertainty, although it does not guarantee protection against losses.
Whether gold suits you depends on your objectives, risk tolerance, and time horizon. Discuss an appropriate approach and sizing with your RHB Relationship Manager.
Terms & Conditions Apply.
Disclaimer:
RHB Multi Currency Account is protected by PIDM up to RM250,000 for each depositor. Multi Currency Account Gold Investment, Multi Currency Account Silver Investment and Investment products are not protected by PIDM.
This article has been prepared by RHB Bank Bhd (“RHB”) and is solely for your information. This article is strictly private, confidential and personal to its recipients and should not be copied, distributed or reproduced in whole or in part, or passed to any third party, without obtaining prior permission of RHB. In preparing this presentation, RHB has relied upon and assumed the accuracy and completeness of all information available from public sources or which was otherwise reviewed by RHB. Accordingly, whilst we have taken all reasonable care to ensure that the information contained in this presentation is not untrue or misleading at the time of publication, we cannot guarantee its accuracy or completeness and make no representation or warranty (whether expressed or implied) and accept no responsibility or liability for its accuracy or completeness. You should not act on the information contained in this article without first independently verifying its contents.
Any opinion, management forecast or estimate contained in this article is based on information available as of the date of this article and is subject to change without notice. It does not constitute an offer or solicitation to deal in units of any fund and does not have regard to the specific investment objectives, financial situation or the particular needs of any specific person who may receive this. Investors may wish to seek advice from a financial adviser/unit trust consultant before purchasing units of any funds. In the event that the investor chooses not to seek advice from a financial adviser/unit trust consultant, he should consider whether the fund in question is suitable for them.
A Product Highlights Sheet (“PHS”) highlighting the key features and risks of the RHB Gold Fund dated 26 February 2024 and RHB Gold and General Fund dated 29 August 2025 are available and investors have the right to request for a PHS. The Information Memorandum has been lodged with the Securities Commission Malaysia (“SC”) who takes no responsibility for its contents. The SC’s approval or authorization, or the lodgement of the Information Memorandum should not be taken to indicate that the SC has recommended or endorsed the fund. Amongst others, investors should compare and consider the fees, charges and costs involved. Investors should also note that the price of units and distributions payable, if any, may go down as well as up. Where a distribution is declared, investors are advised that following the issue of additional units/distribution, the NAV per unit will be reduced from cum-distribution NAV to ex-distribution NAV. Any issue of units to which the Information Memorandum relates will only be made on receipt of a form of application referred to in the Information Memorandum. The printed copy of PHS and the Information Memorandum are available at RHB branches/Premier Centres. Investors are advised that investments are subject to investment risk and that there can be no guarantee that any investment objectives will be achieved. Investors should conduct their own assessment before investing and seek professional advice, where necessary and should not make an investment decision solely based on this article. Subscription of units of the Fund is only open to sophisticated investors.
The Manager wishes to highlight the specific risks of the RHB Gold Fund are Management Risk, Secondary Trading Risk, Currency Risk, and Country Risk. The specific risks of RHB Gold and General Fund are Concentration Risk, Political, regulatory and legal Risk, Counterparty Risk, Market Risk, Foreign exchange and Currency Risk, Derivatives Risk, Liquidity Risk, Small and Medium Capitalisation Companies Risk, Commodities Risk, Broker Risk, Equities Securities Risk, Risk of Using Rating Agencies and Other Third Parties, Investment Management Risk and other general risks are elaborated in the Information Memorandum.
Dual Currency Gold Investment (“DCI Gold”) is a gold and foreign currency linked structured product investment. This structured product has an embedded derivative (the Reference Derivative) that is linked to the performance of gold measured against a selected foreign currency offered by the Bank. DCI Gold is not a principal protected investment.
This article has not been reviewed by the Securities Commission Malaysia (SC).
Member of PIDM.
RHB Bank Berhad 196501000373 (6171-M)